Practical
Travel insurance for New Zealand: what actually needs covering
Here is the fact that surprises everyone: if you are injured in an accident in New Zealand, treatment is largely covered by ACC, the national no-fault accident scheme, tourists included. You cannot even sue for personal injury; the scheme replaced that right. So why buy insurance at all? Because ACC stops at the border and covers only accidents, and the expensive risks live exactly there. Here is what a New Zealand policy genuinely needs.
The four gaps that matter
- Illness: ACC covers accidents, not sickness. A non-resident hospitalised with pneumonia or appendicitis pays real hospital bills. This is the core medical cover you are buying.
- Getting home: medical evacuation and repatriation are the catastrophic line items: a medically escorted flight home to London or New York can run into six figures. No local scheme touches this.
- Cancellation and disruption: you are buying a trip with long flights and weather-dependent moving parts, often months ahead. Cover for cancellation, delay and missed connections is what protects the money itself. Our own model helps here: nothing to pay until confirmation and a 20% deposit cap, detailed on how your money is protected, but flights and insurance are yours to arrange.
- Your gear and the rental car excess: cameras and phones at the small end; at the large end, rental excesses of NZ$3,000 to $7,500 that a policy’s rental vehicle excess cover replaces more cheaply than the counter waiver. Check the policy covers it and skip the daily fee at pickup.
Read the activities clause like it matters
The New Zealand itinerary is precisely the sort that trips exclusion lists: skiing, heli anything, jet boats, bungy, glacier walks, hikes above certain altitudes. Insurers vary wildly on which of these are standard versus add-on. Before buying, list what you actually plan (including the skydive you are pretending you have not decided on) and check each against the policy wording, paying for the winter sports or adventure pack if needed. A claim declined for a named exclusion is the most preventable bad outcome in travel.
The bottom line
We are a travel agency, not an insurance broker, and we hold no licence to sell or recommend specific policies; this page is general information, not financial advice. What we can say from watching hundreds of trips: the travellers who claim are rarely the ones who expected to, the claims that matter are illness and cancellation rather than lost bags, and no guest who needed evacuation cover has ever described the premium as wasted. Buy a real policy from a reputable insurer in your home country, declare your activities, and file this under solved.
What ACC does and does not cover
| Covered by ACC | Needs your policy | |
|---|---|---|
| A fall on a track, a ski injury, a car crash | Treatment in New Zealand, including hospital | Getting home, and the trip you missed |
| Pneumonia, appendicitis, a heart attack | No | Everything: hospital bills are real for non-residents |
| A cancelled trip | No | Cancellation and disruption cover |
| A rental car excess after a gravel chip | No | Rental vehicle excess cover |
| Lost bags | No | Baggage cover, the least important line on the policy |
ACC covers the accident and not the aftermath, and the aftermath is what costs.
Quick answers
Trips that fit
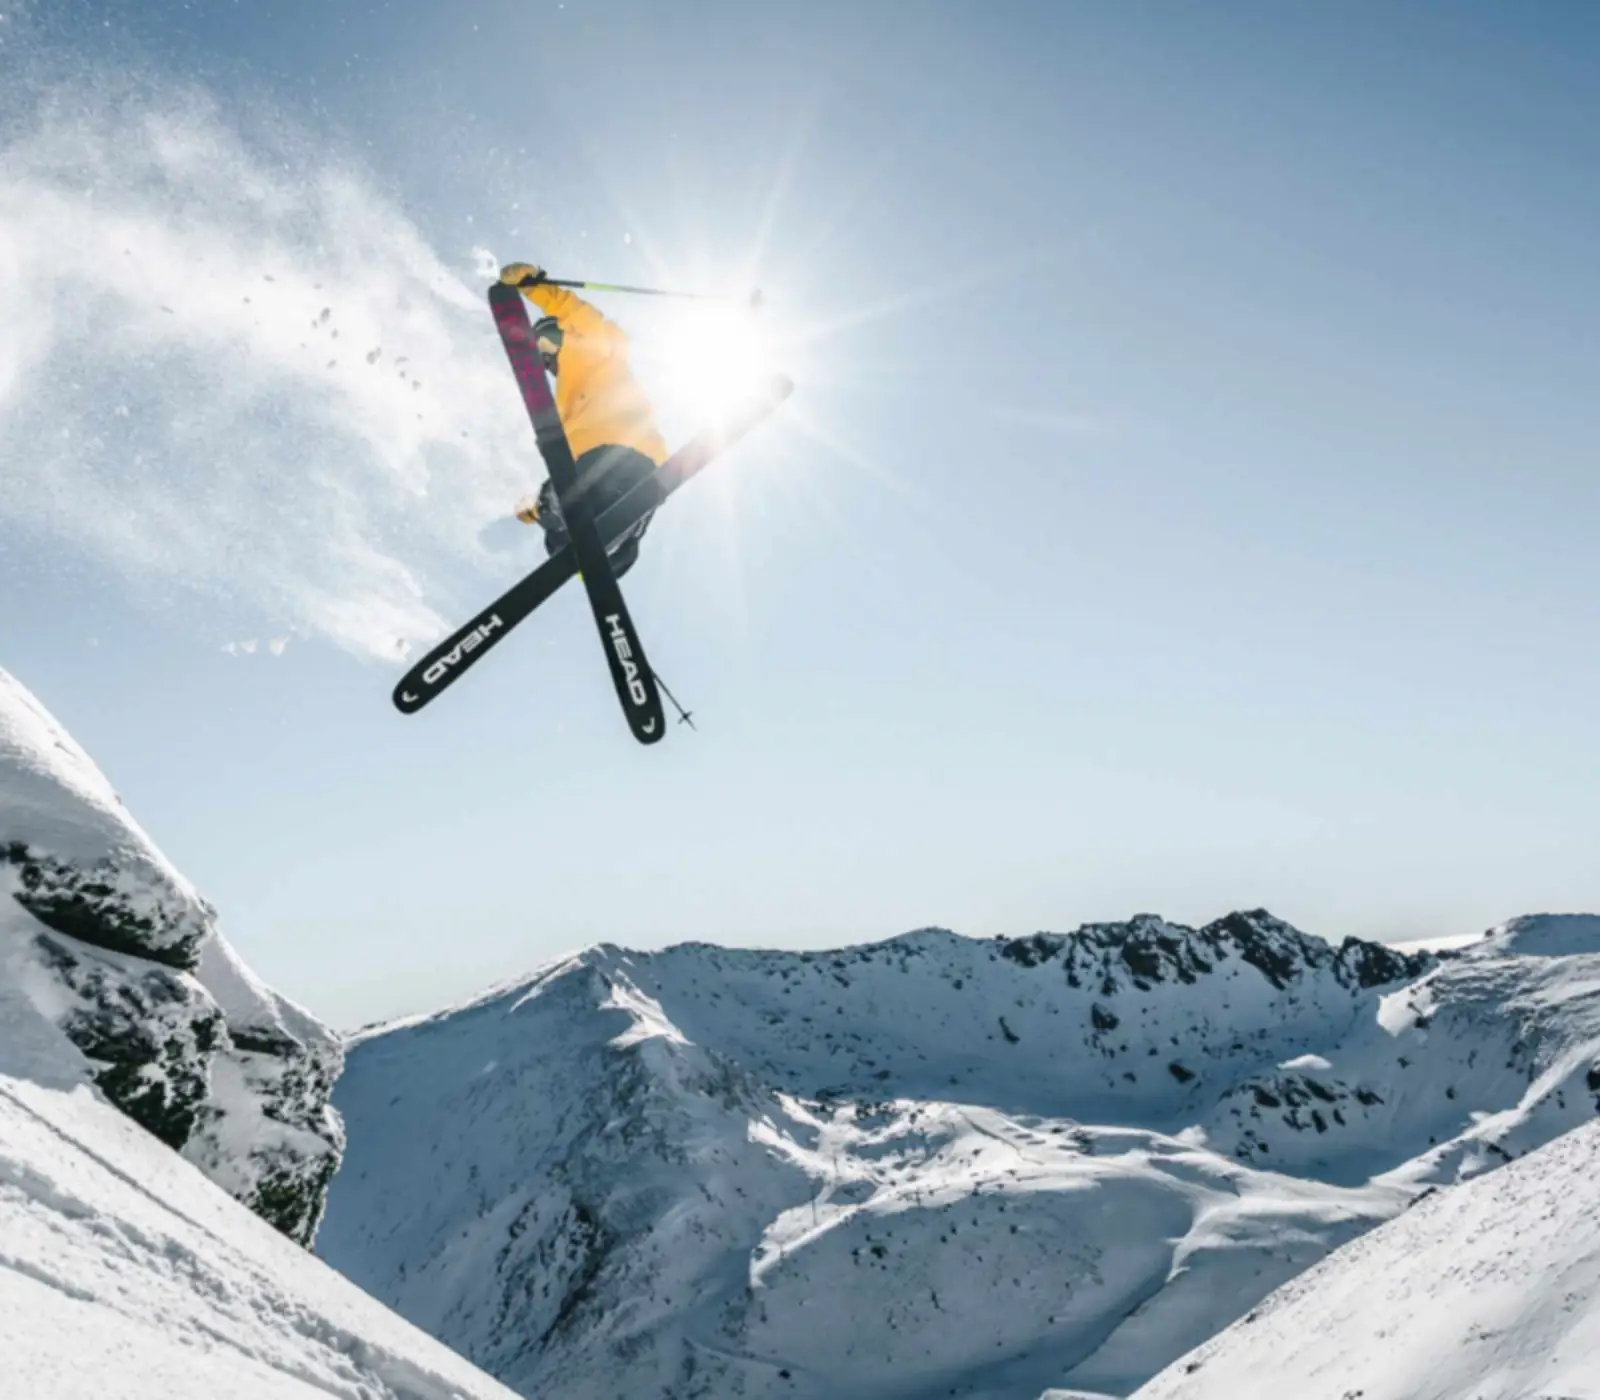
7 Night Queenstown Ski Escape
8 days across the South Island, round trip out of Queenstown, a winter package with the mountain days sorted. Strong on ski packages.
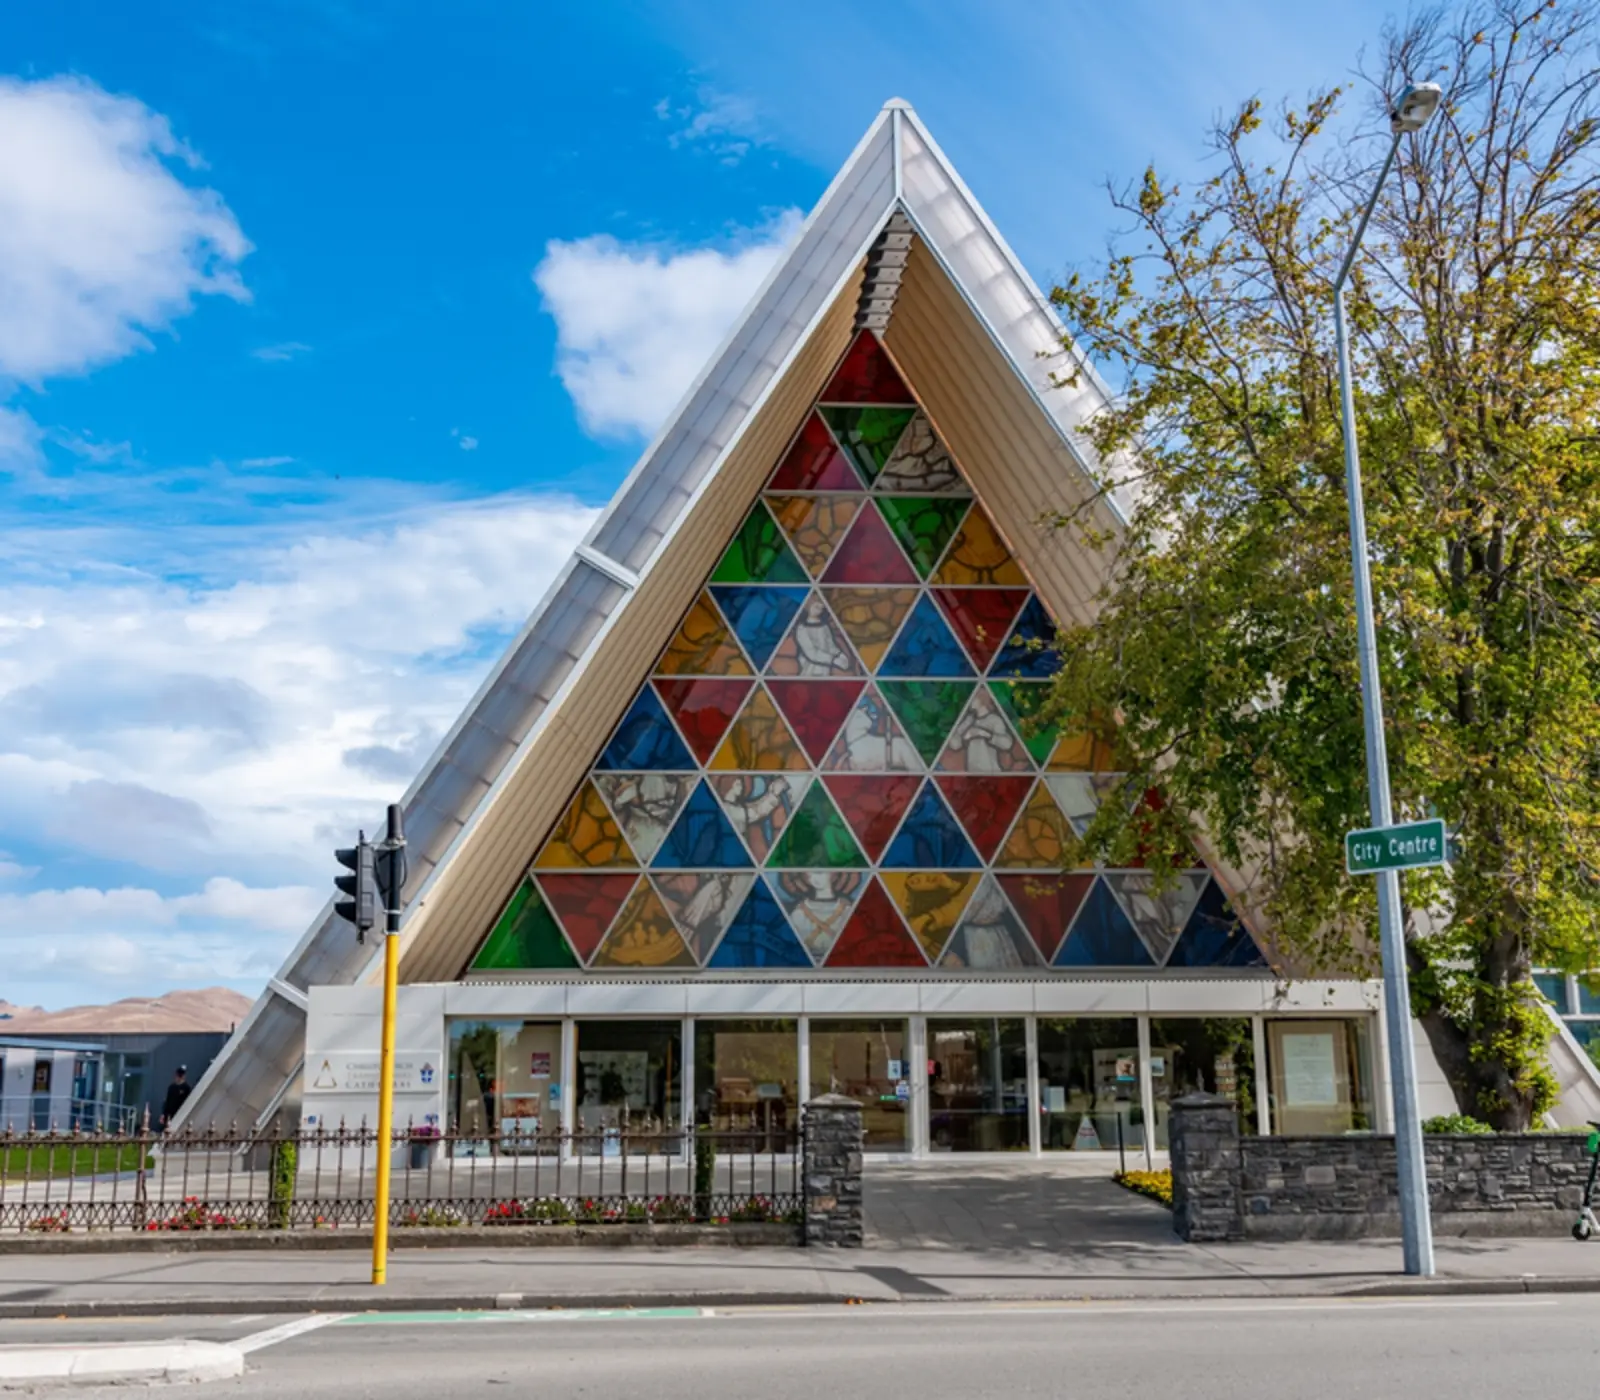
Milford Sound Highlights Tour
7 days across the South Island, a loop from Christchurch, at your own pace behind the wheel. Strong on adventure.
Taste of the South Island
8 days across the South Island, starting and ending in Christchurch, self drive, with every night booked ahead. Strong on classic driving tours.